Transfer pricing rules modernised, and the documentation window cut to 30 days
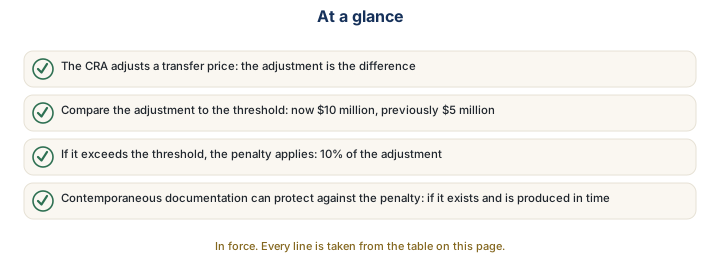
Quick answer: Canada’s transfer pricing rules were aligned more closely with the OECD guidelines. The penalty threshold rose from $5 million to $10 million, and the period to produce documentation on request fell from three months to 30 days.
How it works
When a Canadian business transacts with a related company outside Canada — buying, selling, lending, licensing or charging management fees — the price has to be what unrelated parties would have agreed. That principle is transfer pricing.
It exists because related companies could otherwise shift profit across a border by choosing a price. The CRA can adjust a price it considers wrong and tax the difference.
Canada’s rules were aligned more closely with the OECD guidelines, and two numbers changed. The penalty threshold rose from $5 million to $10 million. The period to produce documentation on request fell from three months to 30 days.
The penalty is 10% of the transfer pricing adjustment, and it applies once the adjustment exceeds the threshold.
How it applies to you
Any Canadian business transacting with a related non-resident. This is not only a large-corporate issue: a small owner-managed company with a related entity abroad is inside these rules.
The threshold increase is relief — a larger adjustment is needed before the penalty applies.
The documentation change is the opposite. Thirty days is not enough time to build a transfer pricing study from scratch, so documentation now has to exist before a request arrives rather than being prepared in response to one.
How to calculate it
How the penalty works:
| Step | Detail |
|---|---|
| The CRA adjusts a transfer price | the adjustment is the difference |
| Compare the adjustment to the threshold | now $10 million, previously $5 million |
| If it exceeds the threshold, the penalty applies | 10% of the adjustment |
| Contemporaneous documentation can protect against the penalty | if it exists and is produced in time |
The changes pull opposite ways: the higher threshold means fewer penalties, but the 30-day window means protective documentation must be ready in advance.
What changed
The penalty is 10% of the transfer pricing adjustment once it exceeds the threshold, now $10 million instead of $5 million — relief. The 30-day documentation window is a real tightening for businesses that document only when asked.
What to do
If you transact with a related company abroad, prepare the documentation now and keep it current. Waiting for a request is no longer a workable approach.
Small owner-managed companies frequently assume transfer pricing is for multinationals. A management fee charged to or by a related foreign company is a transfer price, and the rules apply.
The tightening from three months to 30 days is the practical change here. The threshold increase is welcome, but it does not reduce the need for records.
The practical point. Documentation now has to exist before a request arrives. Thirty days is not enough time to build a transfer pricing study from scratch.
Smaller groups with cross-border related-party transactions feel these rules through their documentation; tax planning for cross-border groups keeps it current.
The terms used on this page
- Transfer price
- The price charged between related companies. It must reflect what unrelated parties would agree.
- Transfer pricing adjustment
- The amount by which the CRA changes a price it considers wrong.
- Contemporaneous documentation
- Records prepared at the time of the transaction, not afterwards. What protects against the penalty.
- Related non-resident
- A company or person outside Canada connected to your business by ownership or control.
Common questions about transfer pricing rules modernised
How long do I have to produce documentation?+
When does the penalty apply?+
Is this change good news or bad?+
When does this start?+
Where this comes from
Every figure on this page is taken from the source below, not from interpretation:
General information, not tax advice. This page explains a change in general terms. It cannot account for your circumstances and does not create a professional relationship. Confirm anything that affects a decision — send an enquiry.
Have a question about this?
Ask free through the quick-question form; a CPA replies within one business day. Need more? A 45-minute Advice Call is $225 plus GST, credited to your first invoice if you become a client within 60 days. Want us to take it on? Send an enquiry.
“…He is very knowledgeable and has saved me tons in taxes by restructuring my group of companies — the best accountant I've worked with in the last 10 years, after switching from three different firms.”